Key Points
- The 2027 limit for 401(k), 403(b), 457 and Thrift Savings Plan contributions rises $1,000 to $25,500, with catch-up contributions of $8,500 at age 50 and $11,750 at ages 60 to 63.
- IRA contributions stay capped at $7,500 for 2027 with a $1,100 catch-up, but the Roth IRA income phase-out climbs to $158,000 to $173,000 for single filers.
- These limits apply to money you contribute in 2027, so raise your payroll election during open enrollment or before your first January paycheck.
The IRS announced on November 12, 2026 that workers can put up to $25,500 into a 401(k) in 2027, up from $24,500 this year. The same limit covers 403(b) plans, government 457 plans and the federal Thrift Savings Plan.
The IRS announcement leaves the IRA limit at $7,500, the same as 2026. You can compare every figure with our 401(k) contribution and income limits page.
The full tables sit in IRS Notice 2026-66 (PDF File). Total employee and employer contributions can reach $75,000, and the wage threshold for mandatory Roth catch-ups rises to $155,000.
These changes come a week after the IRS released the 2027 tax brackets and standard deduction.
| Account Or Limit | 2026 | 2027 |
|---|---|---|
| 401(k), 403(b), 457 And TSP Employee Limit | $24,500 | $25,500 |
| Catch-Up Contribution, Age 50 And Older | $8,000 | $8,500 |
| Catch-Up Contribution, Ages 60 To 63 | $11,250 | $11,750 |
| Total Employee And Employer Contributions | $72,000 | $75,000 |
| Traditional And Roth IRA | $7,500 | $7,500 |
| IRA Catch-Up, Age 50 And Older | $1,100 | $1,100 |
| SIMPLE IRA And SIMPLE 401(k) | $17,000 | $17,500 |
| SIMPLE Higher Limit At Certain Small Employers | $18,100 | $19,100 |
| SIMPLE Catch-Up, Age 50 And Older | $4,000 | $4,000 |
| SIMPLE Catch-Up, Ages 60 To 63 | $5,250 | $5,250 |
| SEP IRA | $72,000 | $75,000 |
| HSA, Self-Only Or Family Coverage | $4,400 / $8,750 | $4,500 / $9,000 |
| Roth Catch-Up Wage Threshold | $150,000 | $155,000 |
Would you like to save this?
What Are The 2027 401(k) Contribution Limits?
The 2027 employee contribution limit for 401(k), 403(b), governmental 457 plans and the TSP is $25,500. Workers 50 and older can add an $8,500 catch-up contribution, for a total of $34,000. Anyone turning 60, 61, 62 or 63 in 2027 gets a higher $11,750 catch-up if the plan offers catch-ups, for a total of $37,250. The $25,500 limit is per person across every 401(k) and 403(b) you contribute to. Governmental 457(b) plans carry their own separate limit, as our comparison of 403(b) and 457 plans explains.
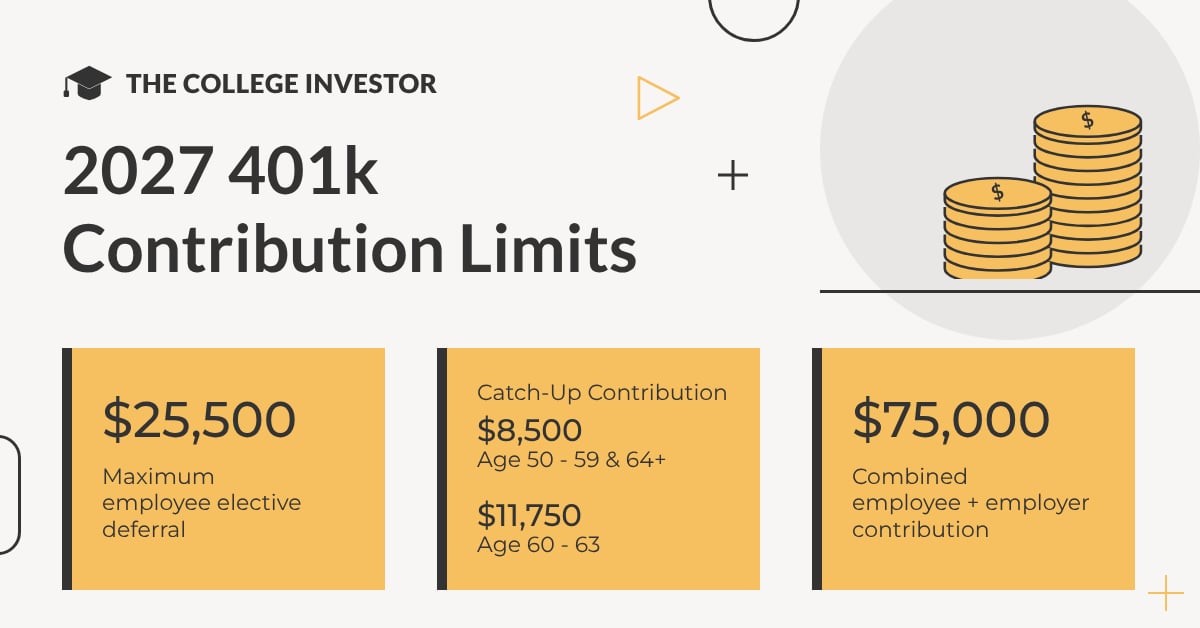
Total contributions from you and your employer, including the match and any profit sharing, can reach $75,000 in 2027, up $3,000. Catch-up contributions sit on top of that cap. The higher ceiling matters most for self-employed savers with a solo 401(k) and for workers who use after-tax money for a mega backdoor Roth.
| Age In 2027 | 401(k) Employee Limit | IRA Limit | Combined |
|---|---|---|---|
| Under 50 | $25,500 | $7,500 | $33,000 |
| 50 To 59, Or 64 And Older | $34,000 | $8,600 | $42,600 |
| 60 To 63 | $37,250 | $8,600 | $45,850 |
Who Must Make Roth Catch-Up Contributions In 2027?
Workers who earned more than $155,000 in FICA wages from their employer in 2026 must make any 2027 catch-up contributions as Roth contributions. The threshold rose from $150,000. That SECURE 2.0 requirement first applied in 2026, and our coverage of the Roth catch-up rule for high earners explains who it hits.
Roth catch-ups go in after tax, so they no longer lower your taxable income that year. If your plan doesn’t offer a Roth option, workers above the threshold can’t make catch-up contributions at all. Ask HR now whether your plan offers a Roth 401(k) before you set your 2027 election.
What Are The 2027 IRA Contribution Limits?
The 2027 IRA contribution limit is $7,500, unchanged from 2026. Savers 50 and older can add $1,100, for $8,600 in total. The limit applies across all of your traditional and Roth IRAs combined, as our IRA contribution and income limits page explains.
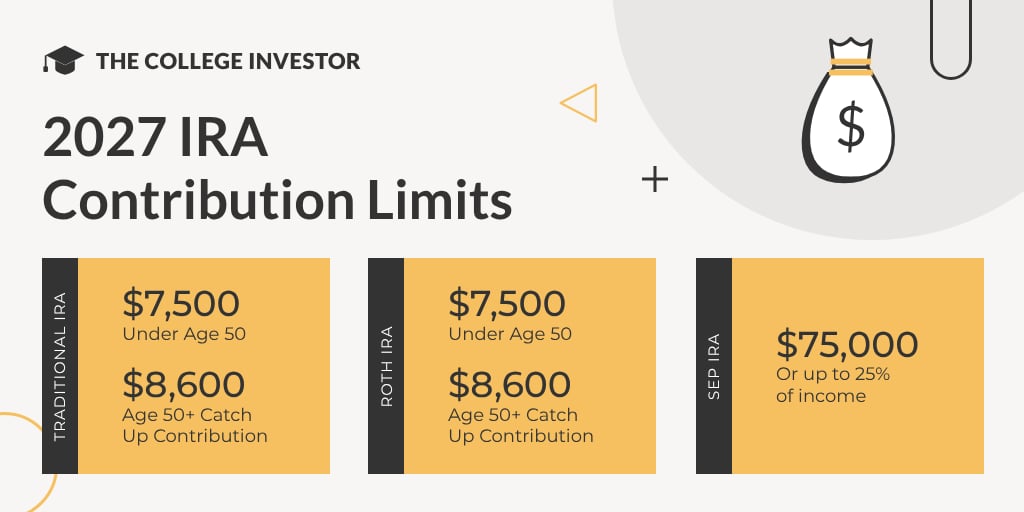
The IRA limit only moves in $500 steps, so it stays flat until inflation pushes it over the next step. A non-working spouse can fund a spousal IRA up to the same limit, as long as the couple files jointly and has enough earned income to cover both contributions.
2027 Roth IRA And Traditional IRA Income Limits
Single filers and heads of household can make a full Roth IRA contribution with modified AGI below $158,000 in 2027, and eligibility ends at $173,000. Married couples filing jointly phase out between $250,000 and $260,000. Savers above those ranges can still use a backdoor Roth IRA.
| Filer | 2026 Range | 2027 Range |
|---|---|---|
| Roth IRA: Single Or Head Of Household | $153,000 – $168,000 | $158,000 – $173,000 |
| Roth IRA: Married Filing Jointly | $242,000 – $252,000 | $250,000 – $260,000 |
| Roth IRA: Married Filing Separately | $0 – $10,000 | $0 – $10,000 |
| Traditional IRA Deduction: Single, Covered At Work | $81,000 – $91,000 | $83,000 – $93,000 |
| Traditional IRA Deduction: Joint, Contributor Covered | $129,000 – $149,000 | $133,000 – $153,000 |
| Traditional IRA Deduction: Joint, Only Spouse Covered | $242,000 – $252,000 | $250,000 – $260,000 |
| Traditional IRA Deduction: Separate, Covered At Work | $0 – $10,000 | $0 – $10,000 |
The traditional IRA deduction phase-out only applies when you or your spouse has a retirement plan at work. A single filer covered at work loses the deduction between $83,000 and $93,000 of modified AGI. Our Roth vs. traditional IRA decision tree helps you pick between the two.
How Do SIMPLE IRA, SEP IRA And HSA Limits Change In 2027?
The SIMPLE IRA limit rises to $17,500 from $17,000, and certain small employers can offer a higher $19,100 limit. SIMPLE catch-ups stay at $4,000 for most workers 50 and older and $5,250 at ages 60 to 63. SEP IRA contributions can reach 25% of compensation, capped at $75,000, per our SEP IRA contribution limits page.
HSA limits for 2027 were set earlier this year at $4,500 for self-only coverage and $9,000 for family coverage, as we reported when the 2027 HSA limits came out. Savers 55 and older can add $1,000. Many savers treat an HSA as a second retirement account.
What Happens To The Saver’s Credit In 2027?
Starting in 2027, the Saver’s Credit no longer applies to 401(k) or IRA contributions. The new $1,000 Saver’s Match replaces it for those contributions, with the federal match deposited into the saver’s retirement account. A footnote in Notice 2026-66 confirms the Saver’s Credit survives only for contributions to ABLE accounts.
For ABLE contributions, the credit’s top income limit rises to $83,000 for married couples filing jointly, $62,250 for heads of household and $41,500 for single filers. Lower-income savers who contribute to a 401(k) or IRA should watch for the match when they file their 2027 return, and we track it alongside the other best tax breaks families can use.
How Do The 2027 Limits Affect Student Loan Payments?
Traditional 401(k) contributions lower your adjusted gross income, and the Repayment Assistance Plan sets your payment from AGI. That makes the new $25,500 limit one of the few legal ways to cut a RAP student loan payment without earning less. RAP charges 1% to 10% of total AGI, based on the $10,000 bracket your income lands in.
We ran a single borrower with no dependents and a $90,000 salary through the 2027 rules, using the standard deduction and no other income. With no 401(k) contributions, the RAP payment is $600 a month. Maxing the 401(k) at $25,500 drops AGI to $64,500 and the payment to $322.50. Federal income tax falls $5,198 under the 2027 federal tax brackets.
| Single Borrower, $90,000 Salary | No 401(k) | $25,500 To 401(k) |
|---|---|---|
| Adjusted Gross Income | $90,000 | $64,500 |
| RAP Rate | 8% | 6% |
| Monthly RAP Payment | $600 | $322.50 |
| Federal Income Tax | $10,690 | $5,492 |
| Yearly Savings | — | $8,528 |
RAP’s brackets create cliffs worth planning around. The same borrower contributing $9,000 lands at $81,000 of AGI and still pays 8%, or $540 a month. Contributing $10,000 drops AGI to $80,000 and the rate to 7%, which cuts the payment to $466.67. That extra $1,000 saves $880 a year in payments, so test your election in our RAP calculator first.
Your RAP payment is generally based on the AGI from your most recent federal tax return, so 2027 contributions show up when you recertify using your 2027 return. Borrowers whose employers offer a student loan 401(k) match can also collect retirement matching dollars on their student loan payments.
What Should You Do Now?
- Raise your 401(k) election for January. Maxing out at $25,500 takes $980.77 per biweekly paycheck, and our order of operations for retirement saving shows where the 401(k) fits.
- Finish your 2026 IRA contribution. You have until April 15, 2027 to fund a 2026 IRA at the 2026 limits, and our best IRA accounts list can help you open one.
- Check your Roth IRA eligibility. Compare your expected 2027 modified AGI with the new ranges, and learn how to calculate your adjusted gross income if you aren’t sure.
- Ask about Roth catch-ups if you earned over $155,000. Your plan needs a Roth 401(k) option for you to keep making catch-up contributions.
- Run the RAP math before open enrollment ends. Our list of pre-tax moves that lower your student loan payment covers the 401(k), HSA and dependent care FSA together.

Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.
Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.
He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.