- A contribution to a parent-owned 529 plan is the best gift of stock for most kids, since it grows tax-free for education and counts for no more than 5.64% on the FAFSA.
- A UGMA or UTMA custodial account lets you give real shares of a favorite company, but the child takes full control of the account at 18 or 21 in most states.
- Family members can now add up to $5,000 a year combined to a child’s Trump Account, which stays invested in U.S. stock index funds until the child turns 18.
Ask a parent what their kids want for Christmas and you’ll usually get a long sigh first. Most parents are already buried in toys, and a child who opens 20 holiday gifts is usually down to one or two favorites by mid-January.
A share of stock is a better gift for most kids. It won’t clutter the house, and it can keep growing long after the toys are gone. As a millennial parent, I’m personally tired of the plastic junk too.
Giving stock in 2026 comes with more choices than it did a year ago. Families can give through a 529 plan, a custodial account or the new Trump Accounts that opened to contributions on July 4, 2026. Here’s how each one works, ranked in the order we’d pick them.
Talk To The Parents First
Ask which accounts the child already has before you buy anything. Adding to an existing 529 plan or custodial account beats opening a duplicate, and our article on how to gift money to a 529 plan lists the questions to ask.
Would you like to save this?
What Is The Best Way To Give Stock To A Kid?
The best way to give stock to a kid in 2026 is a contribution to their 529 plan. The money goes into stock and bond funds, and the growth is tax-free when it pays for education. A parent-owned 529 also has the smallest effect on financial aid, as our breakdown of how a 529 plan affects the FAFSA shows.
A UGMA or UTMA custodial account comes second because it lets you give real shares of a company the child knows, such as Disney or Apple. The trade-off is control, since the child gets the account as a young adult. Our list of the best custodial investment accounts compares where to open one.
The Trump Account is third. It’s a solid long-term gift, but the money is locked until 18 and counts against the child on the FAFSA.
| Gift Option | Best For | Who Owns It | How Much Family Can Give | FAFSA Treatment | Child Gets Control |
|---|---|---|---|---|---|
| 1. 529 Plan | College and other education costs | Account owner, usually a parent | $19,000 per giver before a gift tax return, or $95,000 with a five-year election | Parent asset, up to 5.64% | No, the owner keeps control |
| 2. UGMA/UTMA | Giving shares of a specific company | The child, managed by a custodian | No account limit, gift tax rules apply | Student asset, 20% | At 18 or 21 in most states, up to 25 in some |
| 3. Trump Account | Long-term, retirement-style investing | The child, managed by a parent | $5,000 per child per year, all family and employer money combined | Student asset, 20% | At 18, when it becomes a traditional IRA |
Why Is A 529 Plan The Best Gift Of Stock?
A 529 plan is a tax-advantaged education account, and most plans invest in stock and bond index funds. Earnings grow tax-free, and withdrawals for qualified costs such as tuition and room and board are tax-free too. That tax break is the main edge in any 529 plan vs. brokerage account comparison.
Small gifts add up in a 529. I have two kids, and both have 529 plans that we’ve funded with cash they received for birthdays and Christmas. Each account now holds several thousand dollars. Steady gifts like these are how families reach our 529 savings targets by age.
A parent-owned 529 is a parent asset on the FAFSA, assessed at no more than 5.64%. A grandparent-owned 529 plan isn’t reported on the FAFSA at all, which makes it a strong choice for grandparents with larger gifts. A child with a disability may also have an ABLE account that accepts gifts the same way.
How To Give Money To A Child’s 529 Plan
Most state 529 plans have a gifting page, and many use Ugift, which gives the family a code to share with relatives. You enter the code and pay from your bank account. The money goes straight into the child’s plan. Our article on gifting money to a 529 plan walks through each method.
Backer is a 529 gifting platform where parents set up a page and share a link with family. In our family, it’s the main way grandma and grandpa give money to our kids. Our Backer review explains how it works with existing state plans.
Gift of College sells physical and digital gift cards that the family redeems into a 529 plan, which gives you something to put under the tree. The buyer pays a purchase fee, so compare it with a free online contribution first. Our Gift of College review covers how redemption works.
Upromise is a free cash back program that sweeps shopping and dining rewards into a linked 529 plan. It works well for grandparents who want to add a little all year.
How Much Can You Give To A 529 Plan In 2026?
You can give up to $19,000 to one child’s 529 plan in 2026 without filing a gift tax return, and a married couple can give $38,000. A five-year election lets one person put in $95,000 at once and spread it over five years for gift tax purposes. That election has to be reported on IRS Form 709, as our article on 529 plan contribution limits explains.
How Do You Gift Shares Through A UGMA Or UTMA Account?
To give real shares to a child, the shares go into a custodial account set up under the Uniform Gifts to Minors Act (UGMA) or the Uniform Transfers to Minors Act (UTMA). An adult custodian manages the account, but the money legally belongs to the child from day one. Our breakdown of the pros and cons of UGMA accounts covers the rules.
If the child already has a custodial account at your brokerage, the gift is usually quick. If not, the parent can open one online with the child’s Social Security number and birth date. Teens 13 to 17 can also use a teen brokerage account, which works differently from a UTMA.
You can transfer shares you already own or send cash for the parent to invest. Shares you own carry your original cost basis to the child, so the child owes tax on the full capital gain when they sell.
How To Gift Stock At Fidelity, Schwab, Vanguard And Robinhood
Each major broker handles stock gifts a little differently. Open the box for your brokerage to see the steps, or check our list of the best online stock brokers if you don’t have an account yet.
FidelityGift Form, 1 To 4 Days
- Confirm the child has a Fidelity custodial account, or ask the parent to open one online.
- For a gift to another Fidelity account, fill out the Transfer Between Existing Fidelity Accounts form.
- For a gift to an account at another firm, use the Transfer Shares as a Gift form with the receiving firm’s name and account number.
- Sign the form and upload it to Fidelity, or mail it.
Fidelity lists both forms on its how to gift shares page. Gifts of $10,000 or less to another Fidelity account don’t need a signature guarantee and take one to four days, according to Fidelity’s account services FAQ. Our Fidelity review covers its custodial accounts.
Charles SchwabFractional Shares From $1
- Open a Schwab One Custodial Account online with the child’s birth date and Social Security number.
- Fund the account online.
- Buy most U.S.-listed stocks or ETFs by dollar amount or number of shares, starting at $1 with fractional shares.
- To move shares you already own into the child’s account, call Schwab for the right transfer form.
Schwab markets this as a way to give the gift of ownership in a favorite company. Our Charles Schwab review covers fees and account types.
VanguardOnline Gift Tool, 1 To 3 Days
- Log in and start a gift from a Vanguard nonretirement account. Retirement accounts can’t send gifts.
- Choose a number of shares or a dollar amount, then pick a cost basis method.
- Enter the child’s Vanguard account number. For an account at another firm, enter the firm’s name, its DTC number and the account name and number.
- Submit the gift at least three business days before the last business day of the year if it needs to count for 2026.
Gifts take one to three business days inside Vanguard and up to five to seven days for outside firms, according to Vanguard’s stock gifting page. Our Vanguard review covers its custodial account options.
RobinhoodGifting Link, No Account Needed
- The parent opens a Robinhood custodial account (UTMA) in the app or on the web.
- The parent shares the gifting link from the custodial account’s dashboard.
- You use the link to send cash, stock or ETFs, even if you don’t have a Robinhood account.
- A custodian who moves shares from their own Robinhood account into the custodial account can’t move them back.
Robinhood’s custodial account gifting link is the simplest option for relatives who don’t invest. Our Robinhood review covers the rest of the platform.
What To Know Before You Give Shares To A Custodial Account
A custodial gift is permanent. The child takes full control at the state’s termination age, which is usually 18 or 21 and as late as 25 in some states. The child can spend the money on anything at that point. That loss of control is the biggest difference from a 529 plan, where the owner decides how the money is used.
Investment income in the account is taxed to the child. In 2026, the first $2,700 of a child’s unearned income gets favorable treatment, and anything above $2,700 is taxed at the parents’ rate under the kiddie tax.
On the FAFSA, a custodial account is a student asset assessed at 20%. A $10,000 custodial balance raises the child’s Student Aid Index by $2,000, compared with no more than $564 for the same money in a parent-owned 529.
How Do You Give Money To A Child’s Trump Account?
You give to a Trump Account by contributing through the official Trump Accounts app after the parent claims the child’s account. Family members, friends and employers can add up to $5,000 a year per child combined, and the money is invested in low-cost U.S. stock index funds. Our Trump Accounts article covers the full rules.
Trump Accounts began accepting contributions on July 4, 2026. Treasury also started opening an account for every eligible child under 18 with a Social Security number on or about October 1, 2026. Those automatic accounts can’t take money from relatives until a parent claims the account, as we reported in our coverage of Treasury’s auto-open plan.
How To Give To A Trump Account This Christmas
- Ask the parent first. Confirm the parent has claimed the child’s account in the Trump Accounts app.
- Check the family total. The $5,000 cap covers every contributor combined, so ask how much others have already given in 2026.
- Contribute through the app. Use the official Trump Accounts app or the contribution option the parent shares from it.
- Keep a record. Save the date and amount in case you need it for gift tax purposes.
The $1,000 federal deposit for babies born from 2025 through 2028 doesn’t count toward the $5,000 cap. Parents still have to file Form 4547 to get it, as our article on claiming the $1,000 Trump Account deposit explains.
Most family contributions won’t need a gift tax return. The IRS created a safe harbor for Trump Account contributions in June 2026, so they count toward the annual gift tax exclusion like other gifts.
The Trump Account ranks third because the money is locked until 18 and limited to index funds. The FAFSA treats it as a student asset at 20%, and withdrawals are taxed like a traditional IRA. Our comparison of Trump Accounts vs. 529 plans shows where each one wins.
Can You Give A Framed Share Of Stock?
Yes. GiveAShare sells one real share of stock registered in the child’s name, delivered with a framed, personalized certificate. It’s the gift to pick when the child should have something to unwrap, and our GiveAShare review breaks down what it costs.
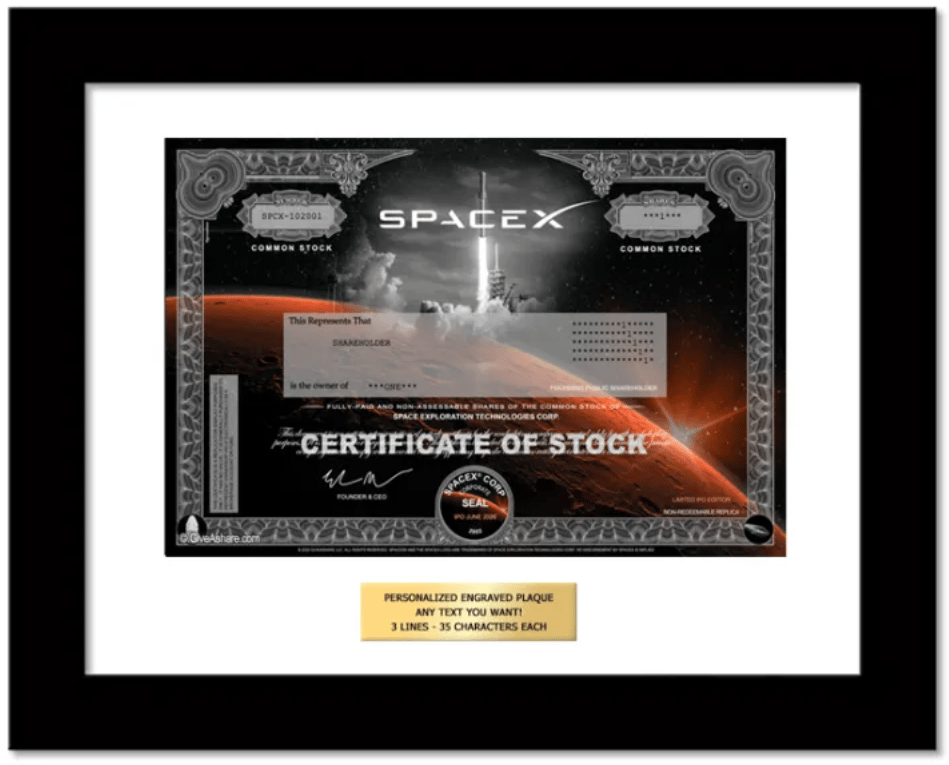
This year’s standout is SpaceX, which went public on the Nasdaq on June 12, 2026. GiveAShare sells a registered SpaceX share with a limited-edition IPO certificate, shown above in a black frame with an engraved plaque.
A GiveAShare gift costs the share’s market price plus a $39 service fee, and frame upgrades add more. The fees are large next to the value of one share, so treat it as a keepsake rather than the main investment. Our roundup of where to buy a real framed stock certificate covers other sellers.
The framed certificate ships within two business days, and the ownership paperwork follows in about 3 to 7 weeks. A Surprise Date option holds registration until a date you choose, such as Christmas morning. Unique Stock Gifts sells a similar framed share if you want to compare prices.
How Much Stock Can You Give Without Gift Tax In 2026?
You can give up to $19,000 to each person in 2026 without filing a gift tax return, and married couples can give $38,000 by splitting gifts. The limit applies per recipient, so a grandparent can give $19,000 to every grandchild. Our gift tax rules article has more examples.
Gifts above $19,000 require IRS Form 709, but you won’t owe gift tax until your lifetime gifts pass $15 million. Your gifts to one child all count toward the same $19,000, including 529, custodial and Trump Account contributions. Shares count at their market value on the day of the gift. Our article on 529 plan contribution limits shows how a five-year election fits in.
Tuition you pay directly to a school doesn’t count toward the $19,000 at all. That makes direct tuition payments a useful extra tool for grandparents helping with college.
When Should You Send A Stock Gift For Christmas?
Start a stock gift by early December so it lands before Christmas and counts for 2026. Brokerages value a gift on the day they process the transfer, so a gift that settles in January counts toward your 2027 limit. Opening a new custodial account adds time, since the account has to be open and funded first.
| Gift | How Long It Takes | What To Do First |
|---|---|---|
| Fidelity Gift To A Fidelity Account | 1 to 4 days | Get the child’s Fidelity account number |
| Vanguard Gift | 1 to 3 business days, 5 to 7 for other firms | Submit 3 business days before the last business day of the year |
| Robinhood Gifting Link | Depends on payment method | Ask the parent to share the link |
| GiveAShare Framed Share | Frame ships in 2 business days, registration in 3 to 7 weeks | Have the child’s legal name and an adult custodian ready |
| Trump Account | Depends on the parent claiming the account | Confirm the account is claimed in the app |
Ask for account details right after Thanksgiving, then send the gift by mid-December. If the parents haven’t opened an account yet, a 529 gifting page or a Gift of College card still works as a last-minute gift on Christmas Eve.
How Can You Teach Kids About The Stock They Own?
The lessons that come with a gift of stock matter more than the share itself. Show the child how to look up their company’s stock price, or read the annual report together when it arrives. Our financial literacy resources have more ideas for every age.
A money book is a good add-on to any stock gift. These are our picks by age, and our list of the best personal finance books has more for older teens.
| Age | Book | Author |
|---|---|---|
| Ages 0-4 | Money A To Z | Scott Alan Turner |
| Ages 5-8 | A Chair For My Mother | Vera B. Williams |
| Ages 9-11 | The Secret Millionaires Club | Andy and Amy Heward |
| Ages 12-14 | The Young Entrepreneur’s Guide To Starting And Running A Business | Steve Mariotti |
| Ages 15-17 | The Money Savvy Student | Adam Carroll |
| Ages 18+ | I Will Teach You To Be Rich | Ramit Sethi |
Gift Of Stock FAQs
Can You Buy Stock For A Child Without A Custodial Account?
Yes, with a framed share from GiveAShare, which registers the share to the child with an adult custodian. You can also contribute to a 529 plan the parent owns. A child under 18 can’t hold a regular brokerage account alone, though some investment accounts for teens let a parent and teen share one.
Can Grandparents Give Stock To A Grandchild?
Yes. Grandparents can contribute to a 529 plan, give shares through a custodial account or add to a Trump Account. A grandparent-owned 529 plan isn’t reported on the FAFSA, which is why our article on how grandparents can save for college favors it.
Can You Gift Fractional Shares Of Stock?
Yes, inside a custodial account at a broker that sells fractional shares, such as Schwab. GiveAShare sells only whole shares. Our article on buying fractional shares lists brokers that offer them.
Does A Gift Of Stock Affect Financial Aid?
It depends on the account. A parent-owned 529 counts for up to 5.64% on the FAFSA, while custodial accounts and Trump Accounts count as student assets at 20%. Our article on 529 plans and financial aid runs the numbers.
Who Pays Taxes When A Child Sells Gifted Stock?
The child pays the tax, based on the giver’s original cost basis. Gains and dividends above $2,700 a year can be taxed at the parents’ rate under the kiddie tax rules.
Editor: Clint Proctor Reviewed by: Claire Tak

Get the latest financial news and actionable insights.
How it works:
- 1Enter your email and subscribe.
- 2Get the latest personal finance and education news delivered every week.
- 3Take control of your finances with real insights.
- 4We won't spam you, ever!

Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.
Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.
He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.