The Question
My daughter is a high school senior with a 4.6 GPA, and I just saw that she can only borrow $5,500 her freshman year. Most of the schools she’s looking at require freshmen to live in the dorms, and $5,500 doesn’t even cover tuition at our in-state school.
Is this a new rule? Are we supposed to take out private loans to make up the difference? It feels like they’re making it impossible for middle-class kids to go to college.
— Julia
Welcome to the Friday mailbag, where we take one reader question and answer it. Have one? Send it to us — details at the bottom.
The Short Answer
The $5,500 first-year limit isn’t new. It has been the cap for dependent undergraduates since the 2008-09 school year.
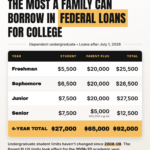
What changed on July 1, 2026 is the parent side: Parent PLUS loans now top out at $20,000 a year and $65,000 total per student. Together, a student and parents can still borrow about $92,000 in federal loans over four years, which is more than most bachelor’s degrees can pay back comfortably.
Would you like to save this?
What The Student Loan Borrowing Limits Actually Are
The amount that dependent undergraduates can borrow rises with each year in school, and the current federal student loan borrowing limits are the same ones families saw in 2008.
Parents can add Parent PLUS loans on top, now subject to the new caps. Here’s what the maximum federal package looks like for a dependent student starting this year:
Maximum Federal Borrowing For A Dependent Undergraduate
| Year In School | Student (Direct Loans) | Parent PLUS | Combined Max |
|---|---|---|---|
| Freshman | $5,500 | $20,000 | $25,500 |
| Sophomore | $6,500 | $20,000 | $26,500 |
| Junior | $7,500 | $20,000 | $27,500 |
| Senior | $7,500 | $5,000Hits the $65,000 cap | $12,500 |
| Four-Year Total | $27,000 | $65,000 | $92,000 |
Student limits have been unchanged since the 2008-09 school year. The student’s lifetime cap is $31,000. Parent PLUS limits of $20,000 per year and $65,000 total apply per student for loans after July 1, 2026. Source: U.S. Department of Education via The College Investor.
The student’s lifetime cap is $31,000, so a fifth year can only be done federally with the students’ own loans. Parent PLUS limits apply per student, not per parent, so two parents cannot each borrow $65,000 for the same child.
Students whose parents are denied a PLUS loan can borrow extra unsubsidized money at the independent-student level, and our Parent PLUS loan explainer covers how that works.
As a side note, we are seeing some schools cap Parent Plus loans at $16,250 per year to allow the parents to spread it equally over 4 years.
These Limits Have Been Frozen Since 2008
It has been nearly two decades since Congress last raised the undergraduate student borrowing limits.
The Higher Education Reconciliation Act of 2005 raised the dependent freshman limit from $2,625 to $3,500 starting in 2007-08, and the Ensuring Continued Access to Student Loans Act of 2008 added another $2,000 a year in unsubsidized loans starting in 2008-09, according to the Government Accountability Office.
That’s where the $5,500, $6,500, and $7,500 comes from, and it hasn’t moved since.
Inflation has been making these numbers more and more out of touch.
Prices are up about 56% since 2008 based on the Consumer Price Index, so the 2008 freshman limit of $5,500 would be roughly $8,560 today and the $31,000 lifetime cap would be about $48,200, according to an inflation calculator using BLS CPI-U data.
Put another way, the student’s own borrowing power has lost about a third of its value in 18 years, which is a big reason more families were leaning on Parent PLUS loans to cover the difference.
What Changed In 2026
The One Big Beautiful Bill Act left undergraduate limits alone, but capped the programs that used to have no ceiling.
Before July 1, 2026, parents could borrow up to the full cost of attendance through Parent PLUS loans. Now the cap is $20,000 a year and $65,000 total per student.
Families already borrowing get a transition window. Parents who took a PLUS loan before July 1, 2026 can keep borrowing under the old rules for the same student in the same program for up to three more academic years, or until expected completion if that’s sooner. Our Parent PLUS timelines for 2026 walks through who qualifies.
Can $92,000 Actually Cover College?
When you add the undergraduate borrowing limits and parent PLUS loan borrowing limits, families can still borrow $92,000 for four years of college with federal student loans.
The College Board puts average published tuition and fees at a public four-year school at $11,950 for in-state students in 2025-26, with a full budget including housing, food, books, and transportation at $30,990, according to College Board’s Trends in College Pricing.
Sticker price also isn’t what most families pay. After grants, first-time, full-time in-state students at public four-year schools paid an estimated $2,300 in net tuition and fees in 2025-26, according to the College Board. In our analysis of what families really pay for college out of pocket, we found that less than 10% of families exceeded $100,000 in out-of-pocket costs for a bachelor’s degree.
If you’re exceeding $92,000, it’s likely that you’re paying for significantly more than education. You’re likely paying for an out-of-state college experience for your child – not just a bachelor’s degree.
Why You Shouldn’t Borrow Past These Limits
The key thing to remember: $92,000 is already more debt than most bachelor’s degrees can support. The most basic rule of thumb is to never borrow more than you expect to earn in your first year after graduation.
More nuanced college ROI data puts the net present value of a bachelor’s degree at being worth between $40,000 and $80,000 in today’s dollars.
The average projected starting salary for computer science majors, the top-paid category, is $81,535, and business majors are projected at $68,873, according to the National Association of Colleges and Employers. Borrowing the full $92,000 means taking on more debt than even the highest-earning first-year graduates make. Our college ROI calculator lets you test this against your student’s intended major.
It all comes down to the monthly payments. Once you graduate college, you’re going to have to start repaying these student loans, and if you don’t earn enough, those monthly payments could be a struggle. Repaid over 10 years, the student’s $27,000 at 6.52% runs about $307 a month, and the parents’ $65,000 at 9.07% runs about $826 a month, for a household total of roughly $1,133.
Our student loan affordability calculator uses the rule of keeping payments below 10% of projected income. For a business graduate earning $68,873, that’s about $574 a month, so the student’s share fits but the full $92,000 doesn’t.
That’s why we recommend families treat the federal limits as a ceiling. Many families end up with the student paying the parents’ loans after graduation, and when that happens, the full package costs nearly 20% of a new graduate’s gross pay.
Our tips on how to minimize college debt are where we’d start before anyone signs for a private loan to supplement even further,
What To Do If The Numbers Don’t Work
- Compare net price, not sticker price. Run every school’s net price calculator and line up the award letters side by side once they arrive. Our ways to pay for college covers every funding source in order.
- Treat a school that needs private loans as a warning sign. If the federal maximum plus grants and savings doesn’t cover it, look elsewhere.
- Look at faster and cheaper paths. Nearly 60 colleges now offer three-year bachelor’s degrees, and some schools offer free tuition below set income levels.
- If you do borrow privately, shop carefully. Compare fixed rates from state-based nonprofit lenders alongside the best private student loans, and keep the total inside the starting-salary math above.
- Start or keep funding a 529 plan. Every dollar saved is a dollar nobody borrows, and our 529 savings targets by age give you a benchmark.
Where People Get This Wrong
The biggest misconception we are seeing is that the $5,500 limit was just imposed. Freshmen have been capped at $5,500 since 2008-09, and the 2026 changes landed on parents and graduate students.
The second mistake is assuming private loans must fill whatever federal loans don’t. Private lenders approve based on credit, usually with a cosigner, and those loans lack income-driven repayment and federal forgiveness options. Our explainer on private student loans covers the tradeoffs.
If your college plan requires $200,000 in private debt for a bachelor’s degree, the problem is the school’s price, not the federal cap, and you should apply elsewhere.
Send Us Your Question
Got a student loan, financial aid, or money question you can’t get a straight answer on? Send it to us and we may answer it in a future Friday mailbag.
Reader Mailbag
Editor: Colin Graves

Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.
Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.
He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.