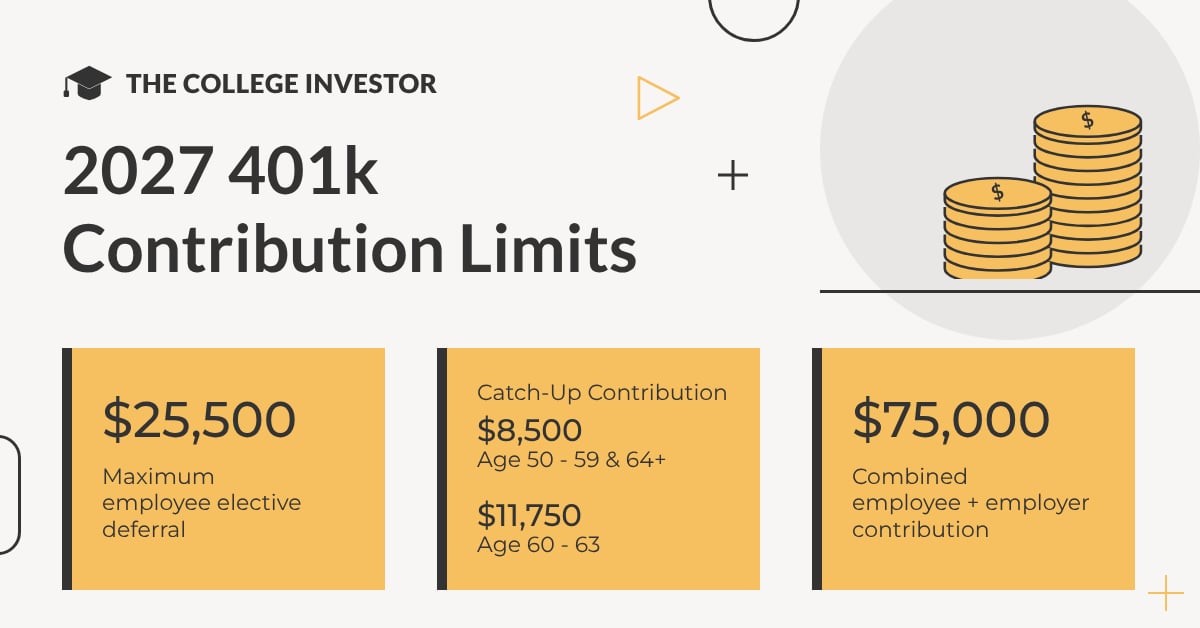
- The 2027 401(k) contribution limit is $25,500, up $1,000 from $24,500 in 2026. Workers 50 and older can add an $8,500 catch-up, and workers aged 60 to 63 get an $11,750 catch-up instead.
- Total contributions from you and your employer can reach $75,000 in 2027, up from $72,000. Catch-up contributions sit on top of that cap.
- The 2026 limits still apply to paychecks through December 31, 2026, so you can still raise your election to max out this year before switching to the 2027 numbers.
The 2027 401(k) contribution limit is $25,500, and the same limit covers 403(b) plans, governmental 457(b) plans and the Thrift Savings Plan. This page shows the 2027 and 2026 401(k) limits side by side, because contributions from your last paychecks of 2026 still count toward the 2026 limit. Our news story on the 2027 IRS limit announcement covers every account type that changed.
You’ll also find the catch-up rules by age, how much to set aside per paycheck to max out, solo 401(k) limits for the self-employed and every limit back to 2018. If you also save in an IRA, the separate IRA contribution and income limits apply on top of your 401(k).
Would you like to save this?
What Are The 2027 401(k) Contribution Limits?
The 2027 401(k) limit is $25,500 for employee contributions, plus an $8,500 catch-up at age 50 and an $11,750 catch-up for anyone who turns 60, 61, 62 or 63 in 2027. Employee contributions include both traditional and Roth 401(k) contributions combined. The figures come from IRS Notice 2026-66 (PDF File).
| Limit | 2026 | 2027 | Change |
|---|---|---|---|
| Employee Contribution Limit | $24,500 | $25,500 | +$1,000 |
| Catch-Up, Age 50 To 59 And 64+ | $8,000 | $8,500 | +$500 |
| Catch-Up, Age 60 To 63 | $11,250 | $11,750 | +$500 |
| Employee Plus Employer Limit | $72,000 | $75,000 | +$3,000 |
| Roth Catch-Up Wage Threshold | $150,000 | $155,000 | +$5,000 |
| Compensation Limit | $360,000 | $375,000 | +$15,000 |
The $75,000 total covers your contributions, your employer match, profit sharing and any after-tax contributions. Catch-up contributions don’t count toward it, so a 60-year-old could see up to $86,750 go into the plan in 2027. After-tax room under that cap is what makes a mega backdoor Roth possible.
What Are The 2026 401(k) Contribution Limits?
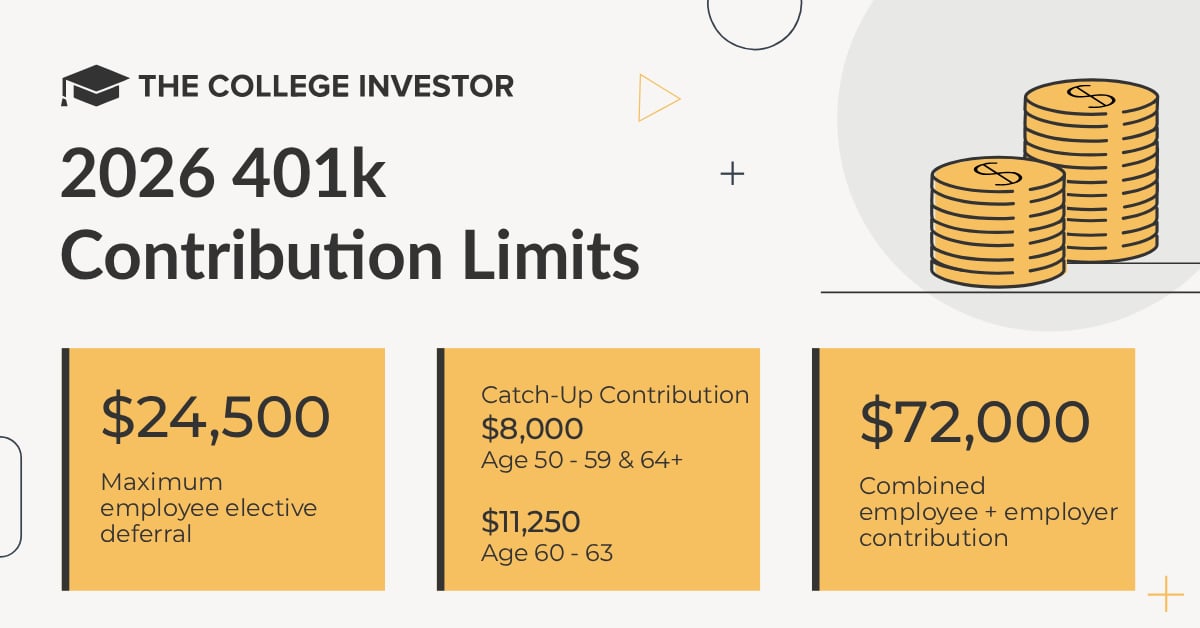
The 2026 401(k) limit is $24,500, with an $8,000 catch-up at age 50 and an $11,250 catch-up at ages 60 to 63. Employee contributions for 2026 must come out of paychecks dated by December 31, 2026, so raise your election now if you want to max out. Our list of year-end money moves covers what else to finish before January.
Employer contributions follow different timing. Your company can deposit 2026 matching or profit-sharing money after year-end, and self-employed savers can make the employer part of a solo 401(k) until their business tax filing deadline, including extensions.
How Much Can You Contribute To A 401(k) By Age?
Your age at the end of the year sets your 401(k) limit. In 2027, workers under 50 can contribute $25,500, workers 50 to 59 and 64 or older can contribute $34,000, and workers who turn 60 to 63 can contribute $37,250. The age 60 to 63 catch-up comes from the SECURE 2.0 Act, and it only applies if your 401(k) plan offers catch-up contributions.
| Age At Year-End | 2026 Employee Max | 2027 Employee Max | 2027 Max With Employer Money |
|---|---|---|---|
| Under 50 | $24,500 | $25,500 | $75,000 |
| 50 To 59 | $32,500 | $34,000 | $83,500 |
| 60 To 63 | $35,750 | $37,250 | $86,750 |
| 64 And Older | $32,500 | $34,000 | $83,500 |
The bigger catch-up stops the year you turn 64, and you drop back to the regular $8,500 catch-up. If you’re in your early 60s, those four years are a strong window to catch up, and our look at how much you should have saved by age can help you set a target.
How Much Should You Contribute Per Paycheck?
To max out a 401(k) in 2027, you need to contribute $980.77 per paycheck if you’re paid every two weeks. Workers 50 and older need $1,307.69, and workers 60 to 63 need $1,432.69. Spreading contributions across the whole year also protects your match, since some plans only match what you put in each pay period. Our income tax calculator shows how much a bigger contribution cuts your federal tax.
| Pay Schedule | Under 50 ($25,500) | Age 50+ ($34,000) | Age 60 To 63 ($37,250) |
|---|---|---|---|
| Weekly (52) | $490.38 | $653.85 | $716.35 |
| Every Two Weeks (26) | $980.77 | $1,307.69 | $1,432.69 |
| Twice A Month (24) | $1,062.50 | $1,416.67 | $1,552.08 |
| Monthly (12) | $2,125.00 | $2,833.33 | $3,104.17 |
Most plans ask for a percentage, not a dollar amount. Someone under 50 earning $100,000 needs to contribute 25.5% to max out, while someone earning $150,000 needs 17%. If maxing out isn’t realistic, contribute at least enough to get the full employer match, which our retirement savings order of operations puts first.
Paying Off Student Loans?
Traditional 401(k) contributions lower your adjusted gross income, which also lowers income-driven repayment plan payments. A single borrower earning $90,000 who maxes out a 401(k) in 2027 cuts a RAP payment from $600 to $322.50 a month, as we showed in our breakdown of the 2027 limits. Test your own numbers in our RAP calculator.
Who Must Make Roth Catch-Up Contributions?
If you earned more than $155,000 in FICA wages from your employer in 2026, any catch-up contributions you make in 2027 must go in as Roth contributions. For 2026 catch-ups, the threshold was $150,000 of 2025 wages. The rule comes from SECURE 2.0, and our coverage of the Roth catch-up rule for high earners explains who it hits.
Roth catch-ups are made with after-tax money, so they don’t lower your taxable income that year. If your plan doesn’t offer a Roth option, workers above the threshold can’t make catch-up contributions at all. Ask your HR team whether a Roth option exists before you set your 2027 election, and see our 401(k) options for high earners if you’re also capped by nondiscrimination testing.
Are There Income Limits For A 401(k)?
No, there’s no income limit to contribute to a 401(k), unlike a Roth IRA. Two income rules can still affect high earners. Plans can only count the first $375,000 of pay in 2027 when figuring employer contributions, up from $360,000 in 2026. Employees who earned more than $170,000 in 2026 count as highly compensated for 2027 plan testing. A failed test can cap or refund their contributions, and our self-employed retirement plans avoid that issue for business owners with no staff.
How Do Solo 401(k) Contribution Limits Work?
A solo 401(k) lets a self-employed person contribute twice: up to $25,500 as the employee in 2027, plus up to 25% of compensation as the employer. Total contributions can’t pass $75,000, plus any catch-up. For sole proprietors, the employer share works out to about 20% of net self-employment earnings after the deduction for half of self-employment tax. Our list of the most popular solo 401(k) providers compares where to open one.
| Step | Amount |
|---|---|
| Net Profit From Schedule C | $150,000.00 |
| Self-Employment Tax | $21,194.32 |
| Minus Half Of Self-Employment Tax | -$10,597.16 |
| Net Earnings From Self-Employment | $139,402.84 |
| Employee Contribution | $25,500.00 |
| Employer Contribution (20% Of Net Earnings) | $27,880.57 |
| Total Solo 401(k) Contribution, Under 50 | $53,380.57 |
That same owner could put only $27,880.57 into a SEP IRA, since a SEP has no employee contribution. Our SEP IRA contribution limits page compares both accounts at several income levels. Employee deferrals for a solo 401(k) must be elected by December 31, and employer contributions can wait until the business tax filing deadline, including extensions.
What If You Have Two Jobs Or Two Plans?
The $25,500 employee limit is per person, not per plan. Contributions to every 401(k) and 403(b) you use in 2027 count toward one shared limit, even across unrelated employers. A governmental 457(b) plan is the exception, since it has its own separate $25,500 limit, as our comparison of 403(b) and 457 plans explains.
The $75,000 total limit works differently. It applies per employer, so a worker with a day job and a side business could fill a workplace 401(k) and still make employer contributions to a solo 401(k). If you go over the employee limit, ask the plan to return the excess by April 15 of the next year, or you’ll be taxed on it twice. Our 401(k) rollover rules help you consolidate old plans after a job change, which makes the limit easier to track.
What Other 401(k) Limits Changed For 2027?
Several plan limits that affect employers and high earners also rose for 2027. These come from the same IRS notice, and most matter for plan testing rather than your own contributions. Our Employee Fiduciary review covers low-cost 401(k) plans for small businesses that have to track them.
| Limit | 2026 | 2027 |
|---|---|---|
| Compensation Limit | $360,000 | $375,000 |
| Highly Compensated Employee Threshold | $160,000 | $170,000 |
| Key Employee Threshold | $235,000 | $245,000 |
| SIMPLE 401(k) Employee Limit | $17,000 | $17,500 |
| Starter 401(k) Employee Limit | $6,000 | $6,500 |
| Pension-Linked Emergency Savings Account | $2,600 | $2,700 |
401(k) Contribution Limit History
Select a year to see its 401(k) limits. Prior-year limits matter when you check an old W-2, fix an excess contribution or track how your savings rate has changed. The 401(k) limit has climbed $7,000 since 2018, and you can see the long-run effect of higher savings in our investment calculator.
2025 401(k) Contribution Limits

| Limit | 2025 |
|---|---|
| Employee Contribution Limit | $23,500 |
| Catch-Up, Age 50+ | $7,500 |
| Catch-Up, Age 60 To 63 | $11,250 |
| Employee Plus Employer Limit | $70,000 |
| Compensation Limit | $350,000 |
2024 401(k) Contribution Limits
| Limit | 2024 |
|---|---|
| Employee Contribution Limit | $23,000 |
| Catch-Up, Age 50+ | $7,500 |
| Employee Plus Employer Limit | $69,000 |
| Compensation Limit | $345,000 |
2023 401(k) Contribution Limits
| Limit | 2023 |
|---|---|
| Employee Contribution Limit | $22,500 |
| Catch-Up, Age 50+ | $7,500 |
| Employee Plus Employer Limit | $66,000 |
| Compensation Limit | $330,000 |
2022 401(k) Contribution Limits
| Limit | 2022 |
|---|---|
| Employee Contribution Limit | $20,500 |
| Catch-Up, Age 50+ | $6,500 |
| Employee Plus Employer Limit | $61,000 |
| Compensation Limit | $305,000 |
2021 401(k) Contribution Limits
| Limit | 2021 |
|---|---|
| Employee Contribution Limit | $19,500 |
| Catch-Up, Age 50+ | $6,500 |
| Employee Plus Employer Limit | $58,000 |
| Compensation Limit | $290,000 |
2020 401(k) Contribution Limits
| Limit | 2020 |
|---|---|
| Employee Contribution Limit | $19,500 |
| Catch-Up, Age 50+ | $6,500 |
| Employee Plus Employer Limit | $57,000 |
| Compensation Limit | $285,000 |
2019 401(k) Contribution Limits
| Limit | 2019 |
|---|---|
| Employee Contribution Limit | $19,000 |
| Catch-Up, Age 50+ | $6,000 |
| Employee Plus Employer Limit | $56,000 |
| Compensation Limit | $280,000 |
2018 401(k) Contribution Limits
| Limit | 2018 |
|---|---|
| Employee Contribution Limit | $18,500 |
| Catch-Up, Age 50+ | $6,000 |
| Employee Plus Employer Limit | $55,000 |
| Compensation Limit | $275,000 |
All Years At A Glance (2018 To 2027)
| Year | Employee Limit | Age 50+ Catch-Up | Total Limit |
|---|---|---|---|
| 2027 | $25,500 | $8,500 | $75,000 |
| 2026 | $24,500 | $8,000 | $72,000 |
| 2025 | $23,500 | $7,500 | $70,000 |
| 2024 | $23,000 | $7,500 | $69,000 |
| 2023 | $22,500 | $7,500 | $66,000 |
| 2022 | $20,500 | $6,500 | $61,000 |
| 2021 | $19,500 | $6,500 | $58,000 |
| 2020 | $19,500 | $6,500 | $57,000 |
| 2019 | $19,000 | $6,000 | $56,000 |
| 2018 | $18,500 | $6,000 | $55,000 |
401(k) Withdrawal And RMD Rules
Withdrawals from a traditional 401(k) are taxed as ordinary income, and taking money out before age 59½ usually adds a 10% penalty. Exceptions include leaving your job in or after the year you turn 55 and a $1,000 yearly emergency withdrawal under SECURE 2.0, if your plan allows it. Borrowing from your 401(k) plan is another option, but you repay the money from future paychecks.
Required minimum distributions now start at age 73, or 75 if you were born in 1960 or later. Missing one triggers a 25% penalty, which drops to 10% if you fix it within two years. Roth 401(k) accounts no longer require distributions while the owner is alive, which makes Roth conversions and Roth contributions more flexible for retirement planning.
401(k) Contribution Limit FAQs
What Is The 401(k) Limit For 2027?
The 2027 401(k) employee contribution limit is $25,500. Workers 50 and older can add $8,500, and workers aged 60 to 63 can add $11,750. Total contributions from you and your employer can reach $75,000, per the IRS 2027 announcement.
Can I Still Contribute To My 401(k) For 2026?
Yes, but only through payroll by December 31, 2026. Unlike an IRA, you can’t make 2026 employee contributions after the year ends. Raise your election now if you want to hit the $24,500 limit, and see our end-of-year financial checklist for other deadlines.
Does My Employer Match Count Toward The $25,500 Limit?
No. Employer matching and profit-sharing contributions count only toward the $75,000 total limit. The $25,500 limit covers your own traditional and Roth contributions. Some companies also match student loan payments with 401(k) dollars.
Can I Contribute To A 401(k) And An IRA In The Same Year?
Yes. The 401(k) and IRA limits are separate, so you could put $25,500 in a 401(k) and $7,500 in an IRA in 2027. A workplace plan can limit your traditional IRA deduction, which our IRA income limits page explains.
What Happens If I Contribute Too Much To My 401(k)?
Ask your plan to return the excess and its earnings by April 15 of the next year. If the money stays in, you pay tax on it the year you contribute it and again when you withdraw it. This happens most often after a job change, so track both plans if you have two 401(k) accounts in one year.
Sources
Editor: Clint Proctor Reviewed by: Ohan Kayikchyan Ph.D., CFP®

Get the latest financial news and actionable insights.
How it works:
- 1Enter your email and subscribe.
- 2Get the latest personal finance and education news delivered every week.
- 3Take control of your finances with real insights.
- 4We won't spam you, ever!

Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.
Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.
He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.