• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer

Navigating Money And Education

  • About
  • Podcasts
  • Social
  • Newsletter
  • Save For College
  • Student Loans
  • Investing
  • Banking
  • Taxes
  • Scholarships
  • Forum
  • Search
Home / News / The Official Student Loan Cohort Default Rate Is 0.4%. Here’s Why That Number Means Almost Nothing.

The Official Student Loan Cohort Default Rate Is 0.4%. Here’s Why That Number Means Almost Nothing.

Updated: October 1, 2026 By Robert Farrington | 8 Min Read Leave a Comment

Many or all of the products featured here may be from our partners who compensate us. This doesn't influence our evaluations or reviews. Our opinions are our own. Investing information is for educational purposes only. Learn more here.Advertiser Disclosure

There are thousands of financial products and services out there, and we believe in helping you understand which is best for you, how it works, and will it actually help you achieve your financial goals. We're proud of our content and guidance, and the information we provide is objective, independent, and free.

But we do have to make money to pay our team and keep this website running! Our partners compensate us. TheCollegeInvestor.com has an advertising relationship with some or all of the offers included on this page, which may impact how, where, and in what order products and services may appear. The College Investor does not include all companies or offers available in the marketplace. And our partners can never pay us to guarantee favorable reviews (or even pay for a review of their product to begin with).

For more information and a complete list of our advertising partners, please check out our full Advertising Disclosure. TheCollegeInvestor.com strives to keep its information accurate and up to date. The information in our reviews could be different from what you find when visiting a financial institution, service provider or a specific product's website. All products and services are presented without warranty.

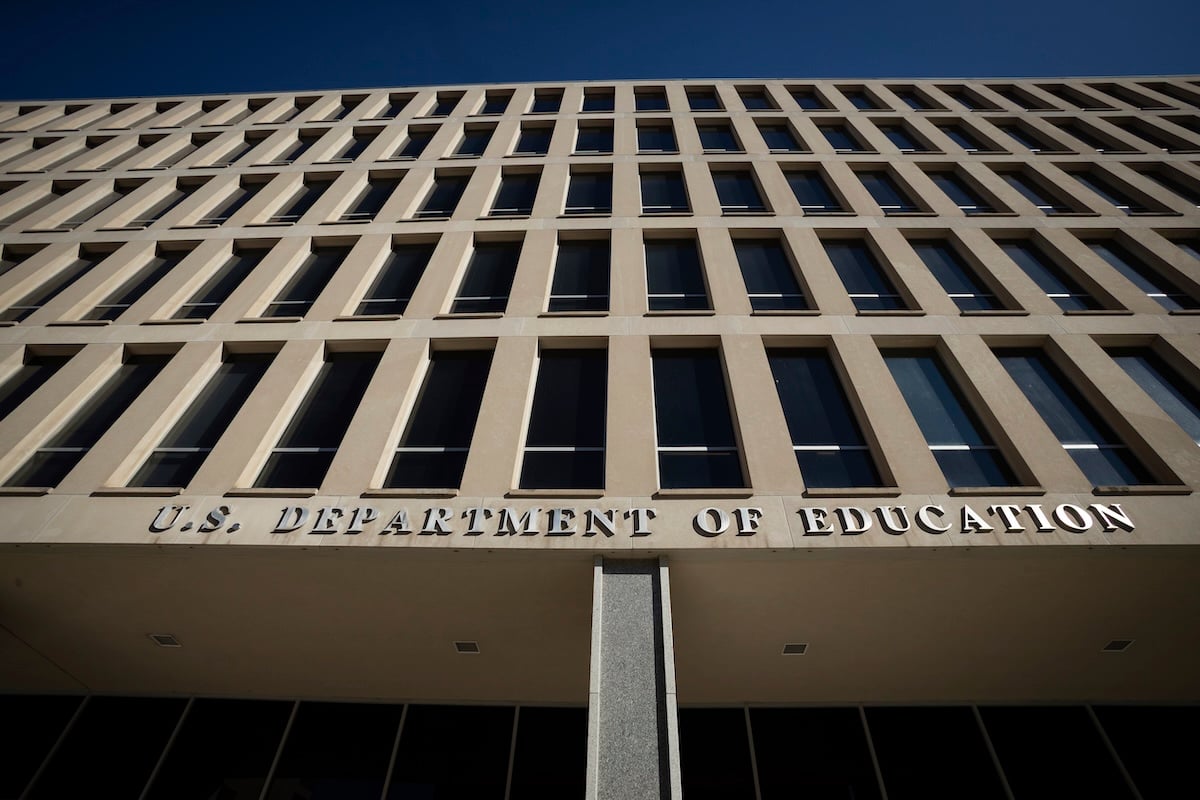
The Department of Education building is seen the morning after Donald Trump signed an executive order dismantling of the department, in Washington, on March 21, 2025. Whether Trump has the authority under the U.S. constitution to close a congressionally mandated agency remains an unanswered question. (Photo by Allison Bailey/NurPhoto via AP)

Key Points

  • The Department of Education’s official FY 2023 cohort default rate is 0.4%, up from 0.0% for FY 2022. Just 14,296 of the 3.37 million borrowers in the cohort defaulted during the three-year measurement window.
  • The rate is low because the pandemic payment pause, the on-ramp, and the SAVE forbearance covered nearly all of the window.
  • The number that matters is coming next year. Draft FY 2024 rates arrive in early 2027 and will be the first calculated with no pandemic protections in place, and roughly 1,800 colleges already have nonpayment rates of 25% or higher.

The Department of Education released its official FY 2023 student loan cohort default rate on September 30, 2026, and the headline figure is 0.4%. Among 3,372,244 borrowers who entered repayment between October 1, 2022, and September 30, 2023, only 14,296 defaulted by September 30, 2025, according to the Federal Student Aid briefing. That is the fourth straight year the national rate has landed at or near zero, but it bears no resemblance to the 9.3 million borrowers currently in default on federal loans.

The gap between those two numbers is confusing a lot of people, including financial aid offices. The explanation is not that borrowers suddenly started paying. It is that the cohort default rate is a narrow, backward-looking measure, and the pandemic-era protections happened to cover nearly every day of the window it measures.

Basically, if you see this number, disregard it. It’s not helpful… yet. Here’s what to know.

Would you like to save this?

We'll email this article to you, so you can come back to it later!

How The Cohort Default Rate Actually Works

A cohort default rate tracks one group of borrowers, those who entered repayment during a single federal fiscal year, and asks what share of them defaulted by the end of the second fiscal year after that. For the FY 2023 cohort, the window opened October 1, 2022, and closed September 30, 2025. Default, for this purpose, means a loan has gone at least 270 days without a payment.

The rate is calculated for every school that participates in federal aid, and the national figure is simply the sum of those schools. The FY 2023 calculation covered 5,417 institutions.

Congress built the measure as an accountability tool: under the Higher Education Act, a school with a CDR of 30% or higher for three consecutive years, or above 40% in a single year, loses access to federal student loans, and for-profit colleges have historically been the schools closest to those lines.

The lag is by design. Because the window runs three fiscal years and the Department needs most of another year to finalize the data, an official CDR describes borrowers who left school roughly four years before the number is published. The FY 2023 rate released this week was calculated on August 1, 2026, about borrowers who started repayment in late 2022 and early 2023.

Official National Student Loan Cohort Default Rate, FY 2012–FY 2023

Share of borrowers entering repayment each fiscal year who defaulted within the three-year measurement window

Line chart of the national cohort default rate falling from 11.8% in FY 2012 to 0.4% in FY 2023
Source: U.S. Department of Education, Federal Student Aid, FY 2023 Official National Student Loan Cohort Default Rate Briefing (Sept. 30, 2026). The FY 2019 through FY 2023 measurement windows were covered in whole or part by the pandemic payment pause (March 2020–Sept. 2023), the 12-month on-ramp, and the SAVE litigation forbearance. Chart: The College Investor.
View as table
CohortOfficial CDR

Why Four Years Of Near-Zero Rates Mean Nothing

The Department’s own briefing says the FY 2023 rate “should be interpreted with caution.” The reason is a stack of three overlapping protections. The pandemic payment pause began March 13, 2020, and ran through September 2023, with no Federal student loans entering default during that stretch.

When payments resumed in October 2023, the Department added a 12-month on-ramp through September 30, 2024, during which missed payments were not reported to credit bureaus and borrowers could not be placed in default. Then the courts blocked the SAVE plan, and the roughly 7 million borrowers enrolled in it were placed in a litigation forbearance that stretched from July 2024 into the fall of 2025.
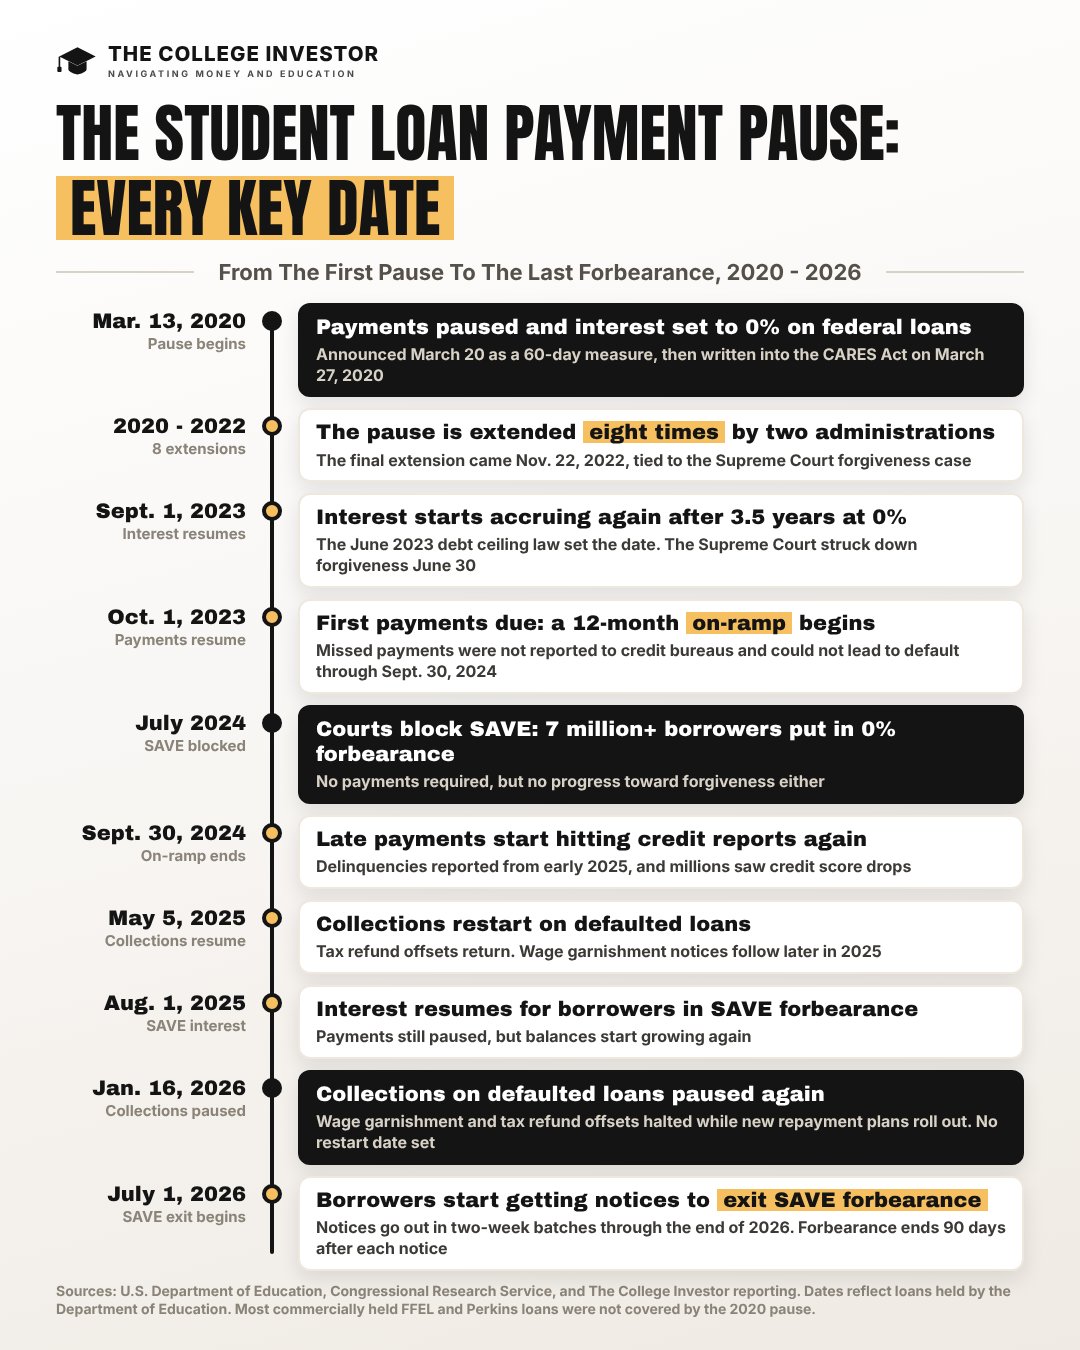
A timeline of the student loan payment pause from March 2020 to present. Source: The College Investor

Lay those dates over the FY 2023 window and the math becomes obvious. The National Association of Student Financial Aid Administrators calculates that FY 2023 borrowers had exactly 365 days, October 2024 through September 2025, in which it was even possible to become delinquent long enough to hit the 270-day threshold, and SAVE borrowers were shielded for most of that year. The FY 2022 cohort had zero such days, which is why its rate was 0.0%. For comparison, the last fully pre-pandemic cohort, FY 2018, defaulted at 7.3%, and FY 2016 came in at 10.1%.

The distortion actually starts one year earlier than most people assume. The FY 2019 cohort entered repayment between October 2018 and September 2019, and its monitoring window ran through September 30, 2021. The pause arrived on March 13, 2020, roughly halfway through, and it did two things at once: payments stopped being required, and the delinquency clock froze for anyone already behind. A borrower who was 200 days late in March 2020 stayed at 200 days for the next three and a half years instead of crossing the 270-day line.

That left FY 2019 borrowers with somewhere between five and 17 months of real exposure, depending on when they entered repayment, instead of the usual three years. The result was a 2.3% rate, down from 7.3% the year before. The national rate had been declining slowly since FY 2012, when it peaked at 11.8%, but a five-point drop in a single cohort is not a trend. It is a window that closed early, and every cohort since has had the same problem or worse.

What The Numbers Show Underneath The 0.4%

Even inside a near-zero year, the data is showing a few signals. Borrowers at for-profit schools defaulted at 0.8%, double the 0.3% rate at public and private nonprofit institutions, with 4,821 of 576,634 proprietary-school borrowers in default. Foreign schools posted the lowest rate at 0.2%.

The cohort itself also shrank. The number of borrowers entering repayment fell 4.4% from the FY 2022 cohort, a drop of 156,845 people, and the decline at for-profit schools was 13.4%. The number of participating schools fell by 88, to 5,417, with for-profits accounting for 83 of the lost institutions.

Those shifts track with enrollment and lending trends The College Investor has covered, where fewer students are borrowing even as balances for those who do keep rising.

The Number Schools Should Be Watching Instead

The Department is telling colleges to focus on a different metric: the nonpayment rate. That figure measures the share of a school’s Direct Loan borrowers who entered repayment between January 2020 and May 2025 and are more than 90 days delinquent. The Department refreshed that data on September 22, 2026, using August 2026 figures, and the results show a much bigger issue.

Approximately 1,800 institutions have nonpayment rates at or above 25%, according to the Department’s announcement. That is consistent with the broader delinquency picture: as of June 30, 2026, Federal Student Aid data showed 9.3 million borrowers in default holding $234 billion, with another 1.5 million in late-stage delinquency and roughly 20% of borrowers in active repayment more than 30 days behind.

The nonpayment rate carries no sanctions. The CDR does, and the Department’s announcement spells out what it expects: draft FY 2024 rates will be issued in early 2027, and the official FY 2024 rates next fall will be “the first such release following the full expiration of pandemic-era flexibilities.”

The Department has asked schools above 25% to update their default prevention plans, attend an October 13 webinar, and complete a new self-paced training track on CDRs. The FY 2024 cohort entered repayment between October 2023 and September 2024, and its window closes September 30, 2026, meaning the outcome is already largely baked in.

What This Means For Borrowers And Families

For an individual borrower, the CDR has no direct effect on your loan. It does not change your interest rate, your repayment plan options, or whether your loan is in good standing. Its effect is on the school, and only when it crosses the sanction thresholds.

The indirect effects are the ones worth paying attention to. A school that loses federal loan eligibility loses the revenue most of its students use to pay tuition, and sudden college closures strand students mid-degree.

For borrowers who are behind, it’s a different story. Collections resumed in May 2025, wage garnishment is restarting, and the New York Fed has documented credit score drops averaging 91 points for borrowers who went from current to default.

A borrower already in default can get out through rehabilitation or consolidation, and the Department now runs an online portal for both.

The FY 2023 rate is being measured on misleading data. The FY 2024 and FY 2025 rates will be the first real test of how the post-pandemic repayment system, including the new RAP plan and the end of SAVE, is working.

Editor: Colin Graves

Robert Farrington
Robert Farrington

Robert Farrington is the founder of The College Investor and is widely recognized as one of the nation’s leading voices on student loan debt and saving for college. He holds an MBA from UC San Diego Rady School of Management and has spent over 15 years researching, writing, and advising on student loans, 529 plans, financial aid programs, and saving and investing for young professionals.

Robert has been featured in the The New York Times, The Wall Street Journal, The Washington Post, NBC News, and Forbes, where he has been a regular personal finance contributor for over a decade. His work combines both professional expertise and personal experience – he successfully navigated his own student loan repayment journey and has helped thousands of readers do the same.

He is committed to making the intersection of personal finance and education transparent and accessible. You can learn more about Robert on the About Page or on his personal site RobertFarrington.com.

Please Share And Support

  • Facebook
  • X
  • LinkedIn
  • Reddit
  • Flipboard
  • Bluesky
  • Print
  • Email
Editorial Disclaimer: Opinions expressed here are author’s alone, not those of any bank, credit card issuer, airlines or hotel chain, or other advertiser and have not been reviewed, approved or otherwise endorsed by any of these entities.
Comment Policy: We invite readers to respond with questions or comments. Comments may be held for moderation and are subject to approval. Comments are solely the opinions of their authors'. The responses in the comments below are not provided or commissioned by any advertiser. Responses have not been reviewed, approved or otherwise endorsed by any company. It is not anyone's responsibility to ensure all posts and/or questions are answered.
Subscribe
Notify of
0 Comments
Oldest
Newest Most Voted

Primary Sidebar


Add The College Investor as a Preferred Source on Google
As Featured In

Social Media

Popular Posts

Student Loan Forgiveness Programs

Student Loan Forgiveness Programs In 2026: Every Way To Qualify

529 Plan By Age

How Much Should You Have In A 529 Plan By Age

SAI Chart EFC Chart

2027 – 2028 Student Aid Index (SAI) Chart And Calculator

Net Worth of Millennials

Average Net Worth Of Millennials By Age (2026 Update)

A dynamic infographic illustration titled "The College Investor: Best Side Hustles" features a stylized figure of a man in a black shirt on the lower center, gesturing with an open hand towards a list of icons on a light blue panel on the right. The background is a mix of white and light blue, adorned with scattered light blue polka dots and minimalist black line art shapes like plus signs and triangles. The man's gesture highlights three black icons arranged vertically: a funnel, a camera, and a chef's hat, each accompanied by five blue stars, suggesting high ratings for these side hustle categories. This visual aims to help readers identify worthwhile side hustles with high earning potential, good scheduling flexibility, and growth opportunities, tying into the article's focus on effective ways to earn extra money to achieve financial goals like paying off student loans or saving for retirement.

20 Best Side Hustles of 2026: Ranked by Earnings, Flexibility, and Growth

Photograph of the historic Vassar College, a private, coeducational, liberal arts college in the town of Poughkeepsie, New York. Founded in 1861 by Matthew Vassar

30 Most Expensive Colleges in 2026: Tuition Tops $72,000 at Every School on the List

A man with blonde hair, dressed in a white collared shirt, sits relaxed on a wooden bench with his hands clasped behind his head, gazing out over a calm body of water at sunset. A silver laptop is visible next to him on the bench, suggesting he has just finished working or is taking a break while his investments generate passive income. The warm, soft light of the setting sun creates a tranquil atmosphere, emphasizing the freedom and peace of mind associated with achieving financial independence through passive income streams. This image perfectly illustrates the article's core message about earning money without continuous active effort, highlighting the desired outcome of strategic monetary or time investments.

30 Passive Income Ideas To Build Wealth In 2026

IRS Refund Schedule

IRS Tax Refund Calendar And Schedule 2026 (Updated)

Side Hustle Ideas

54 Side Hustle Ideas To Make Money Fast

wait to repay your student loans

For-Profit College Student Loan Forgiveness List

Ultimate Guides

How To Fill Out The FAFSA | Source: The College Investor

How To Fill Out The FAFSA: 2027-28 Step-By-Step Guide

Student Loan Forgiveness

The Full List Of Student Loan Forgiveness Programs By State

Using a 529 Plan For yourself

529 Plans: The Ultimate Guide To College Savings Plans

Student Loans and Financial Aid By State

Student Loan And Financial Aid Programs By State

Student Loan Advice

The Definitive Guide To Student Loan Debt

Latest Research

MINNEAPOLIS/USA - July 23: Tate Labratory on the campus of the University of Minnesota. The University of Minnesota is a university in Minneapolis and St. Paul, MN and the 6th largest university in the USA.

Why Is College So Expensive? 5 Forces Behind Rising Tuition Costs

EVANSTON, IL,USA - JUNE 20, 2021 - Entrance sign and gardens to Northwestern University.

Are Expensive Colleges Worth It? New Data on Price, Selectivity, and Graduation Rates

Profile views of a young woman and a young man facing each other, set against a grey background adorned with hand-drawn lightbulbs. A single bright yellow lightbulb glows centrally between them, symbolizing the realization or "bright idea" regarding the shifting gender dynamics in higher education. This visual metaphor accompanies an analysis of the growing gender gap in college degree attainment, where women now outpace men in earning Associate's, Bachelor's, Master's, and Doctoral degrees. Source: The College Investor

Gender Gap in College Degrees: 50 Years of Data Explained

Institutional Merit Grants

Who Gets Merit Based Scholarships At Private Colleges?

This image depicts a stylized graphic representing college education and its perceived value, set against a dynamic background of gold and black shapes. A prominent white circular icon in the center showcases a black graduation cap with a tassel, positioned above a rolled-up diploma tied with a ribbon, symbolizing academic achievement and a college degree. To the left, the top of a person's head and shoulders are visible, suggesting a student or individual considering their educational path. The background features various abstract shapes, including long, rounded rectangles in black and gold, smaller white dots, and thin diagonal lines, creating a sense of movement and modern relevance. This visual reinforces the article's theme about Americans weighing in on college costs, education policy, and the worth of a college degree in 2025, particularly given that public sentiment on college value is currently low.

New Poll Reveals How Americans Feel About College

Footer

Who We Are

The College Investor® provides the latest news and analysis for saving and paying for college, student loan debt, personal finance, banking, and college admissions.

Connect

  • Social
  • Contact
  • Newsletter
  • Advertise
  • Press & Media
  • Helpful Calculators

About

  • About
  • In The News
  • Research
  • Editorial Guidelines
  • How We Make Money
  • Archives

Social

Copyright © 2026 · The College Investor® · 2514 Jamacha Rd, Ste 502, El Cajon, CA 92019

Privacy Policy ·Terms of Service · Do Not Sell or Share My Personal Information

wpDiscuz