Key Points
- 1Federal law lists trusts as a reportable asset, and the Department of Education says a trust is the beneficiary’s asset even when the beneficiary can’t touch the money yet.
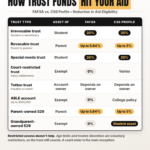
- 2Who reports the trust depends on its type. A revocable trust is the grantor’s asset and an irrevocable trust is the beneficiary’s. Student assets reduce aid by 20% on the FAFSA and 25% on the CSS Profile, versus up to 5.64% and 5% for parent assets.
- 3The exemptions are narrow: trusts restricted by court order, trusts with contested ownership, trusts the beneficiary may never receive, and trusts the beneficiary doesn’t know about. Age limits and trustee discretion don’t count.
A trust fund set up by a parent or grandparent can be one of the most valuable gifts a student ever receives, and one of the most expensive when the financial aid forms come due. With a few exceptions, a trust must be reported as an asset on the FAFSA and CSS Profile financial aid application forms. This reduces the student’s eligibility for need-based financial aid.
How much it hurts depends on whose asset it is. A trust reported as a student asset cuts eligibility for need-based aid by 20% of its value on the FAFSA, while a trust reported as a parent asset cuts eligibility by no more than 5.64%. A $100,000 trust in the student’s name can cost up to $20,000 a year in aid eligibility on the FAFSA alone. The overall premise is that if a student has money, they should use that money to pay for college. The dilemma with trusts is that students may not always have access to that money.
The rules hinge on details families rarely think about: whether the trust is revocable, whether a court imposed the restrictions, and whether the beneficiary even knows the trust exists. Here’s how trust funds are treated, which trusts are exempt, and what you can do if a trust you can’t touch is shrinking your financial aid package.
Trust Fund Treatment At A Glance
| Trust type | Reported as asset of | FAFSA impact | CSS Profile impact |
|---|---|---|---|
| Irrevocable trust (student beneficiary) | Student | 20% | 25% |
| Revocable trust (parent grantor) | Parent | Up to 5.64% | Up to 5% |
| Special needs trust | Student (beneficiary) | 20% | 25% |
| Court-restricted trust | Exempt | 0% | Varies |
| Totten trust (payable on death) | Account owner | Depends on owner | Depends on owner |
| ABLE account (≤ $100,000) | Exempt | 0% | Depends on college policy |
| Parent-owned 529 plan | Parent | Up to 5.64% | Up to 5% |
| Grandparent-owned 529 plan | Exempt | 0% | Reported as student asset |
Requirement To Report Trust Funds As Assets
The Higher Education Act of 1965 requires student and parent assets to be considered when determining eligibility for need-based financial aid. [20 USC 1087oo, 1087pp and 1087qq] Those assets feed directly into the Student Aid Index (SAI), the number colleges use to decide how much need-based aid you qualify for.
Assets are defined at 20 USC 1087vv(f)(1) as including trust funds. The same definition covers the checking, savings and investment accounts most families already expect to report.
The term “assets” means the amount in checking and savings accounts, time deposits, money market funds, investments, trusts, stocks, bonds, derivatives, securities, mutual funds, tax shelters, qualified education benefits (except as provided in paragraph (3)), the annual amount of child support received and the net value of real estate, vacation homes, income producing property, and business and farm assets, determined in accordance with section 1087rr(c) of this title.”
The Application and Verification Guide (AVG), which is published annually by the U.S. Department of Education, states that “Trust funds are an asset of the named beneficiary of the trust, even if the beneficiary’s access to the trust is restricted.” The CSS Profile asks about trusts directly, including who established the trust and whether any income or principal is currently available to the student.
Revocable Vs. Irrevocable Trusts
Both revocable and irrevocable trusts must be reported as assets on financial aid application forms. The main impact is on who reports the trust fund as an asset.
A revocable trust fund can be changed or dissolved by the grantor of the trust. Since the grantor retains control over the trust fund, it must be reported as an asset of the grantor of the trust on the FAFSA if the grantor of the trust is the student or a dependent student’s parent.
An irrevocable trust fund cannot be changed or dissolved by the grantor of the trust. As such, it must be reported as an asset of the beneficiary of the trust.
When Trust Funds Are Exempt From Reporting
The value of a trust fund must be reported as an asset even if there are restrictions on access to the trust. As noted in the AVG, “If the settlor of a trust has voluntarily placed restrictions on its use, then the beneficiary should report its present value as an asset.”
Voluntary restrictions often include age restrictions on access to the trust and limitations on what the trust fund can be spent on. Voluntary restrictions also include the trustee’s discretionary control over the timing and purpose of distributions from the trust fund. This is the same logic that makes UGMA and UTMA custodial accounts count in full as student assets even though the child can’t necessarily access the money until adulthood.
The main exception to reporting a trust fund on the FAFSA occurs when the trust fund has been involuntarily restricted by a court order, such as might occur in a personal injury settlement. As noted in the AVG: “If a trust has been restricted by court order, however, the beneficiary should not report it. An example of such a restricted trust is one set up by court order to pay for future surgery for the victim of a car accident.“
If access to an asset is temporarily frozen by a court, the asset is not reported on financial aid application forms until access to the asset is restored. For example, if a decedent’s will is being contested, the applicant cannot report the inheritance until the estate is settled. This includes testamentary trusts, which are trust funds established by the will. The FAFSA is not updated when access to the asset has been resolved.
Another example is when ownership of the asset is being legally contested, such as during the pendency of divorce proceedings. As noted in the AVG: “If ownership is contested, the asset should not be reported on the FAFSA form.“
If receipt of the trust funds is indeterminate, the trust is not reported as an asset on financial aid application forms until receipt of the funds becomes determinate. For example, a trust fund might require the beneficiary to earn a college degree by a specified date. If the beneficiary does not earn the college degree by that date, the trust fund is given to a charity. Another example might involve a future coin toss or the trust fund assets exceeding a specified threshold.
If an applicant does not know about the existence of a trust fund, they have no obligation to report it as an asset. However, more than two-thirds of states require a trust fund to be disclosed to beneficiaries once the trust fund becomes irrevocable.
State Disclosure Rules Affecting Trust Funds
36 states and the District of Columbia have adopted the Uniform Trust Code (UTC), which requires such disclosure. These states include Alabama, Arizona, Arkansas, Colorado, Connecticut, District of Columbia, Florida, Hawaii, Illinois, Kansas, Kentucky, Maine, Maryland, Massachusetts, Michigan, Minnesota, Mississippi, Missouri, Montana, Nebraska, New Hampshire, New Jersey, New Mexico, North Carolina, North Dakota, Ohio, Oregon, Pennsylvania, South Carolina, Tennessee, Utah, Vermont, Virginia, West Virginia, Wisconsin and Wyoming.
Some UTC states, however, allow grantors of a trust to waive the trustee’s obligation to tell the beneficiaries of the trust’s existence before the beneficiary’s 25th birthday.
Eight states allow silent or quiet trusts, which do not require disclosure of a trust until a triggering event occurs, such as the beneficiary reaching a particular age or the grantor of the trust dies or becomes incapacitated. These states are Alaska, Delaware, Nevada, New Hampshire, South Dakota, Tennessee, Wyoming and Utah. Four states (Ohio, Florida, Michigan and Texas) allow more limited quiet trust rules.
How Is A Trust Fund Reported?
If there are multiple beneficiaries of the trust, then each beneficiary must report their proportional share of the trust unless the trust document specifies a different allocation. For example, if three siblings are listed as the only beneficiaries of a trust fund, then each sibling reports one third of the trust fund’s value as an asset on the FAFSA, using the same net worth rules that apply to any other asset.
Sometimes, a trust fund will split ownership of the income and principal of the trust. For example, one beneficiary might receive the income of the trust for a number of years, after which another beneficiary receives the remaining principal of the trust. In such a situation, each beneficiary must calculate the net present value of the future payments they will receive from the trust. An example of such a trust is one that pays the income from the trust to the beneficiary during their lifetime and then gives the principal to a charity after the beneficiary’s death.
The net present value is calculated by discounting each future payment to the present value using a discount rate. The net present value is the amount of money invested now that will yield the future payment. A common discount rate is the return on investment of a risk-free investment, such as U.S. Treasuries of comparable maturity.
The sum of the net present value of the principal and income from a trust should be the same as the current value of the trust. It is best to consult with an accountant when determining the net present value of the income and principal from a split-interest trust.
Payments from a trust are reported as income to the recipient in the year received.
Examples Of Trust Funds
Common examples of trust funds that must be reported as assets on the FAFSA and CSS Profile include:
- Crummey Trusts
- Living Trusts
- Section 2503(c) Minor’s Trusts
- Special Needs Trusts
The beneficiary of a Special Needs Trust does not have access to the money in the trust, as the trustee manages the money and decides when and how to pay it out. But, this is considered a voluntary restriction on access to the trust fund and therefore the trust fund must be reported as an asset on financial aid application forms.
An ABLE account, however, is not reported as an asset on the FAFSA. Amounts in an ABLE account up to $100,000 are disregarded in determining eligibility for means-tested federal benefit programs. (An ABLE account must be reported as an asset on the CSS Profile form. Each college, however, has the discretion to choose to ignore ABLE accounts as assets.)
Blind trusts, charitable trusts, insurance trusts, Medicaid trusts, and spendthrift trusts must be reported as assets on financial aid application forms.
A Totten Trust, also known as a Payable on Death account, must be reported as an asset on financial aid application forms. But, instead of being reported as an asset of the beneficiary, it is reported as an asset of the grantor of the trust (the account owner).
Although 529 plans are technically structured as state-sponsored trusts, they follow different reporting rules than other trust funds.
- 529 plans must be reported on the FAFSA as an asset of the account owner, not the beneficiary. If a 529 plan is owned by a dependent student, it is reported as though it were a parent asset on the FAFSA. If the beneficiary of a 529 plan is a sibling, the 529 plan is not reported as an asset on the FAFSA. If the owner of a 529 plan account is someone other than the student or parent, it is not reported as an asset on the FAFSA. For example, if a 529 plan is owned by a grandparent, aunt, uncle or the non-custodial parent, it is not reported as an asset on the FAFSA. Starting with the 2024-2025 FAFSA, qualified distributions from such a 529 plan are not reported as income on the FAFSA.
- The CSS Profile has a different treatment for 529 plans. All 529 plans that list the student as a beneficiary must be reported as an asset on the CSS Profile, regardless of the account owner.
Impact Of A Trust Fund On Financial Aid Eligibility
The impact of a trust fund on eligibility for need-based financial aid depends on whether it is reported as a student or parent asset. If it is reported as a student asset, it will reduce aid eligibility by 20% of the asset value on the FAFSA and 25% of the asset value on the CSS Profile. If it is reported as a parent asset, it will reduce aid eligibility by up to 5.64% on the FAFSA and up to 5% on the CSS Profile. You can see how a trust changes your own numbers with our SAI calculator.
If access to a trust fund is restricted, it may prevent the student from liquidating the trust fund, reducing aid eligibility year after year. Applicants can appeal to the college financial aid administrator in special circumstances involving trust funds, but most financial aid administrators will not make an adjustment. If filing an appeal, provide the financial aid administrator with a copy of the trust document.
Sometimes, state law may override restrictions on use of a trust fund. For example, some states allow a trust fund to be used to pay for the education of the beneficiary, regardless of the terms of the trust. Court intervention may be required to override the terms of the trust fund, which is a conversation to have with the attorney who drafted the family’s estate planning documents.
In addition to a trust fund being reported as an asset, income received by the beneficiary from the trust fund will be reported as income to the recipient on the FAFSA.
Editor: Robert Farrington

Mark Kantrowitz is an expert on student financial aid, scholarships, 529 plans, and student loans. He has been quoted in more than 10,000 newspaper and magazine articles about college admissions and financial aid. Mark has written for the New York Times, Wall Street Journal, Washington Post, Reuters, USA Today, MarketWatch, Money Magazine, Forbes, Newsweek, and Time. You can find his work on Student Aid Policy here.
Mark is the author of five bestselling books about scholarships and financial aid and holds seven patents. Mark serves on the editorial board of the Journal of Student Financial Aid, the editorial advisory board of Bottom Line/Personal, and is a member of the board of trustees of the Center for Excellence in Education. He previously served as a member of the board of directors of the National Scholarship Providers Association. Mark has two Bachelor’s degrees in mathematics and philosophy from the Massachusetts Institute of Technology (MIT) and a Master’s degree in computer science from Carnegie Mellon University (CMU).